Advanced Market Report
Infinite Technologies, Inc. (iTec) announces the impending release
of a major update to its LCD/FPD Market Strategies 2001 report.
The latest English language revision, due for release in April
2002, forecasts that the global flat panel display market will
be valued at 7.8 trillion Yen ($60 billion) in 2006, of which
4 trillion Yen ($31 billion) will be TFT-based displays and 230
billion Yen ($1.77 billion) organic EL displays. The active matrix
organic EL display market is expected to take off from 2004 onwards.
Special report features:
(1) Wide-ranging forecasts are detailed not only for large-screen
FPDs, but also for small and medium screen sizes. Production trends,
color screen trends, and size trends are presented on a global
basis through to 2006.
(2) An overview of profitability trends and industry restructuring
challenges in the LCD industry is included.
(3) We have added forecasts for display applications based on
market value. Moreover, we have gone into even more detail in
terms of screen size analysis compared with our 2001 report. Special
sections also focus on "Strategic Data for the Cellular Telephone
and PDA Market" and "Profitability Analysis for Small-
and Medium-Size Displays."
REPORT CONTENTS
O. Executive Summary
1. Business Chances in the Small-Screen LCD Market. Focus on Cellular
Telephones and PDAs.
<Conclusions>
・The unit price for W-CDMA terminals in 2005 will be of the order
of PDC terminals in 2001. Display panel costs will fall to a level
of just over half that of 2001.
・The LCD market for PDA and cellular telephone applications in
2006 will grow significantly to 960 billion Yen ($7.4 billion)
by 2006. However, there are questions regarding industry profitability
owing to the sheer number of market players.
・The average return on sales of the five largest small- and medium-size
screen LCD manufacturers is likely to reach 8.2%.
2. Global Demand Forecasts for FPD/LCD/CRT (1999-2006)
The following display types are covered in detail:
TN-LCD, STN, Color-STN, aSi-TFT,
High Temperature pSi-TFT,
Low Temperature pSi-TFT, Reflective LCD, Plastic LCD, PDP, O-ELD,
I-ELD, VFD, FED, LED, DMD, CRT, Flat CRT
Each display type is analyzed in terms of: (1) market volume forecast,
(2) market value forecast, (3) price forecast, (4) application
breakdown, (5) screen size breakdown, (6) color display trend,
(7) manufacturer trends, (8) technology trends, (9) miscellaneous
information.
<Conclusions>
・The global FPD market registered insignificant growth in 2001
due to adverse market conditions for TFTs. Market value was 3.1
trillion Yen ($23.8 billion). By 2006, we estimate the market
will grow to 7.8 trillion Yen ($60 billion).
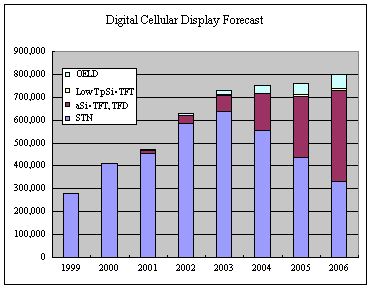
・Color STN display demand will expand initially due to use in
the fast-growing cellular telephone market, but from 2003, we
expect the market to start to contract.
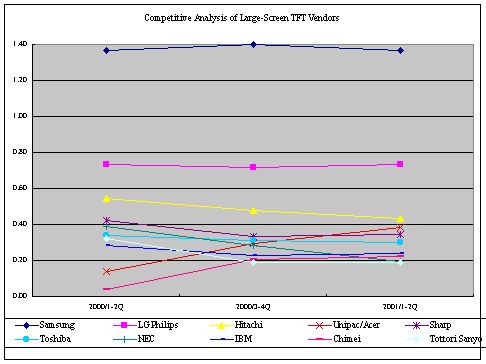
・The overall large aSi-TFT display market posted a lower value
in 2001 compared with 2000. Taiwanese players such as Acer, Unipac,
and Chimei increased their market presence.
・Shipments of small and medium screen size aSi-TFT displays finally
started to pick up as the cellular market developed, but over-competition
quickly emerged.
・Companies expanded their capacities for low temperature pSi-TFTs,
and the market size jumped to 85 billion Yen ($650 million). The
overall market should challenge the 300 billion Yen ($2.3 billion)
level by 2006.
・The delayed roll out of digital television means PDPs are still
primarily employed in non-TV applications. Prices will continue
on their downward trend.
・Motorola's adoption of organic ELDs has seen their utilization
grow. We foresee full color variants and active matrix drivers
taking off from 2003 onwards. Initially, market development will
begin with self-emitting and fast response types.
・Inorganic ELDs have unique attributes
such as earthquake resistance, fast response, and usability under
cold temperatures. Numerous challenges, however, remain with regards
to cost, brightness, and color display.
・VFDs are a stable, mature market, but through penetration into
color display segments, we see a gradual increase in the market.
・Use of FEDs in TVs is expected to commence in 2003.
・CRTs will benefit from the trend towards wide-screen TVs, but
we foresee tough times ahead as the price differential with LCD
monitors continues to contract. Expect a number of manufacturers
to exit the business.
3. FPD/LCD/CRT Demand Forecasts by Product
<Segments covered>
(1) Large (10" plus): PC Monitors, Large Notebook PCs, TVs,
Non-PC Monitors, Others (word processors, etc.)
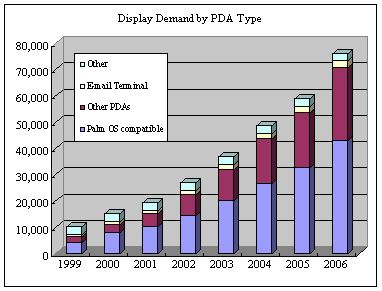
(2) Small and Medium: Small Notebook PCs, PDAs, Handheld PCs,
Home Web Terminals, Digital Cellular Telephones, Pagers, Small
TVs/Portable DVDs, Video Cameras, Digital Still Cameras, Projectors,
AV Front Panels, Remote Controllers, Pocket Games, Pachinko, Car
Displays/Navigation Systems, Instrument Panel Displays, Factory
Automation/Measurement Equipment, Medical Equipment, POS/ECR,
Clocks/Watches, Copy Machines, Calculators, Other
Each segment is analyzed in terms of: (1) display demand, (2)
national and regional demand (3) demand by display format, (4)
screen size breakdown, (5) color display trend, (6) technology
trends, (7) user trends, (8) miscellaneous information.
<Conclusions>
・Falling prices for 15" TFT PC monitor displays will see
the market grow significantly. By 2006, we estimate 42% of PC
monitors will be FPDs. Expect high growth rates for high resolution
monitors and 17-18" monitors.
・The mainstream screen size for notebook PCs will center on 14-15"
for A4 types, and 10-12" for B5 types. In 2006, 28% of monitors
will be high resolution.
・While digitalization of television is expected to create competition
between CRTs plus set-top boxes, PDPs, and LCDs, we foresee that
CRTs will dominate as stand alone types, while LCDs will feature
prominently as 10-20" wall-mounted units, and PDPs will occupy
the wall mounted segment with larger screen sizes.
・Reflective LCDs are coming to dominate in mobile devices, but
we see market segmentation depending on the end-use application
in the medium term.
・While demand growth for cellular applications was unimpressive
in 2001, we expect that the impending shift to the CDMA format
will reignite market growth in 2002. By 2006, we forecast that
48% of cellular telephones will employ aSi-TFT displays and 8%
OELD displays. We expect the 2" panel market in this market
segment to collapse.
・High temperature pSi-TFT displays will be employed in viewfinder-type
cameras and data projectors in the audio-visual segment, while
we also foresee significant growth in low temperature pSi-TFT
demand. We expect OELDs to make considerable gains in audio visual
front panels and projectors.
・Car displays are undergoing a transformation from dedicated instrument
panel indicators, navigation, and VICS and ETC displays, to versions
that integrate car PCs and TVs. Amidst a plateau in automobile
production volume, we see a high probability of between two and
six displays being mounted per one vehicle, making this segment
one with considerable potential.
4. LCD Cost and Profitability Trends/Simulation of How to Achieve
Profitability
(1) Analysis of profitability and competitiveness of LCD manufacturers,
(2) Trends in unit cost composition of TFT modules, (3) Simulation
of how to achieve profitability
<Conclusions>
・The moment that large TFT display makers finally achieved profitability
across-the-board in fiscal 1999 (ending March), they were confronted
with a slowdown in fiscal 2000. We foresee a high probability
that fiscal 2001 (ending March) will see many manufacturers bleed
red ink.
・Sales and administration costs as Taiwanese manufacturers are
only 5-7% of total costs, so therefore they should turn profits
on a operating basis in 2001. On a net profit basis, the Taiwanese
will overpower their Japanese and Taiwanese competitors due to
the taxation incentives they enjoy.
・Without significant industry restructuring, we foresee tough
times for market players.
The English language version of Global Liquid Crystal
Display/Flat Panel Display Market Strategies 2002 is available
as of April through Infinite Technologies' global marketing agent,
Asia Info Tsushinsha, in either hard copy or .pdf document format.
The report is priced at US$2,500- Japanese language
version is also available for the same price.
Infinite Technologies, Inc. (iTec) was established in April 1999
by George Ohgaki, previously a consultant at Yano Research Institute.
The company's staff of six specialize in analysis of three key
areas: information technology; electronics; and new materials.
Major projects to date include consultation on marketing and R&D
strategies at major Korean electronic component manufacturers,
a study on merger & acquisition targets for European companies
in the Japanese automotive component manufacturer sector, a survey
on computer peripherals technology, an analysis of management
at major U.S. semiconductor manufacturers, and a report on B-to-B
and B-to-C E-commerce in Japan.
For more information, please contact:
ai.comm
Asia Info Tsushinsha Pte.
Ltd.
95 South Bridge Road
#10-32 Pidemco Centre
Singapore 058717
Tel. 65-535-5300
Fax. 65-226-3269
Email: ai-comm@excite.co.jp
To place an order, please fill out your contact details below
and fax back to +65-226-3269 (Singapore). We will invoice
you and ship the report on receipt of your payment by cashier's
check or telegraphic transfer.
Name:
Company:
Title:
Mailing address:
Telephone:
Fax:
Email:
Sample data (Source: Infinite Technologies, 2002)
-Desktop monitor demand forecast by screen size (1000 units)
| - | - | - | - | - | - | - | - | - | - |
| - | 1999 | 2000 | 2001 | 2002 | 2003 | 2004 | 2005 | 2006 | CAGR |
| <CRT> | - | - | - | - | - | - | - | - | - |
| 14" | 10,500 | 6,500 | 1,000 | 500 | 0 | 0 | 0 | 0 | -100.0% |
| 15" | 31,490 | 26,500 | 24,500 | 18,000 | 16,000 | 14,000 | 12,000 | 9,000 | -16.4% |
| 17" | 45,600 | 58,500 | 67,500 | 72,500 | 75,000 | 75,000 | 75,000 | 75,000 | 7.4% |
| 19" | 5,500 | 6,800 | 7,700 | 11,500 | 14,000 | 17,500 | 17,800 | 18,200 | 18.6% |
| 21"- | 3,300 | 2,980 | 3,580 | 3,770 | 4,100 | 6,200 | 6,500 | 6,800 | 10.9% |
| Total | 96,390 | 101,280 | 104,280 | 106,270 | 109,100 | 112,700 | 111,300 | 109,000 | 1.8% |
| <STN> | - | - | - | - | - | - | - | - | - |
| 10-12" | 20 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | -100.0% |
| <aSi-TFT> | - | - | - | - | - | - | - | - | - |
| 10-12" (12.1") | 10 | 0 | 0 | 0 | 0 | 0 | 0 | 0 | -100.0% |
| 13" | 130 | 50 | 20 | 0 | 0 | 0 | 0 | 0 | -100.0% |
| 14" | 1,650 | 600 | 400 | 100 | 0 | 0 | 0 | 0 | -100.0% |
| 15" | 2,280 | 6,000 | 11,600 | 17,900 | 25,900 | 39,000 | 51,500 | 66,000 | 61.7% |
| 16-18" | 100 | 300 | 880 | 1,800 | 2,800 | 4,400 | 6,600 | 9,600 | 91.9% |
| 19-20" | 0 | 20 | 60 | 140 | 200 | 400 | 600 | 1,000 | - |
| 21-24" | 10 | 30 | 40 | 60 | 100 | 200 | 300 | 400 | 69.4% |
| Total | 4,180 | 7,000 | 13,000 | 20,000 | 29,000 | 44,000 | 59,000 | 77,000 | 51.6% |
| <pSi-TFT> | - | - | - | - | - | - | - | - | - |
| 15" | 0 | 0 | 0 | 0 | 50 | 90 | 150 | 300 | - |