TOKYO, JAPAN -- FEBRUARY 15, 2001 -- Following on from
its ground breaking LCD/FPD Market Strategies 2001 report released
last year, Tokyo's Infinite Technologies, Inc. is pleased
to announce the impending release of its latest report
Advanced Market Report
Based on currently ongoing in-depth investigations on the ground
in Tokyo and elsewhere in Japan, the English language version
of the report will be released at the end of April.
Innovative features of LCD Components Supply/Demand 2001
include:
(1) The latest forecasts of TFT supply/demand trends and component
supply trends that
could prove to be bottlenecks for future market growth.
(2) Analysis of market structures and dominant players for various
display components.
(3) The challenges that LCD makers will face in implementing their
production plans and pricing
strategies based on component supply/demand scenarios.
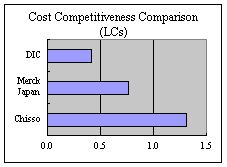
4) Relative competitiveness of component suppliers.
Report Contents and Summary
Executive Summary
I. Analysis of bottlenecks to LCD market growth and overview
of components market
1. The Components Industry
--The market for the 28 major LCD components in 2000 was valued
at JPY770 billion ($6.7 billion). In 2005, this value will grow
to around JPY1 trillion ($8.7 billion),
--The overall components market size was 40% that of the LCD industry
in 2000. In 2005, it will be an estimated 30%.
--Average component prices will fall by 10% per annum. Cost cutting
at LCD makers and the nature of the components industry mean component
price drops will be faster that LCD price drops.
2. Analysis of component bottlenecks that threaten the growth
of the TFT market.
--Supply/demand balance for major components will generally tend
towards the tight side.
--In particular, there may be a shortage of glass substrates and
driver ICs of about 10% in 2005.
3. Analysis of component prices
--Components resistant to price falls are prism sheets, ITO targets,
CF overcoats, rubbing cloths, and sealants. For these components,
there is either a monopolistic producer, or three dominant players
with one possessing a relative market share of in excess of 1.5.
--Components expected to fall in price are CFs, BLs, liquid crystals,
photoresists, and polarizing sheets. These components can either
be made in-house or in lower-cost offshore economies, or alternatively,
the relative market share of the top player in a market dominated
by three players is less than 1.5.
--Competitive major players include Corning, Toppan, Nitto Denko,
3M, J-Energy, Sekisui, Nissan Chemical, and Stanley.
4. Component price pressures based on TFT cost forecasts.
--Japanese TFT makers need to cut component costs to 30% of overall
costs by 2005 to
secure profitability.
--They will find it tough to reduce other costs such as depreciation.
II. TFT Supply/Demand Balance Forecast
1. TFT Production Capacity Trends
2. Supply/demand balance simulation.
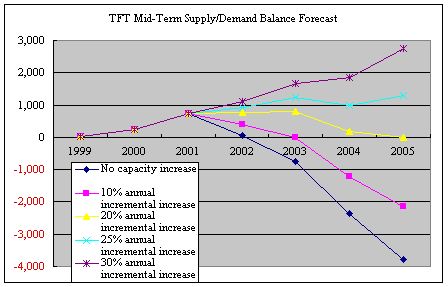
Supply/demand scene in 1Q/2001 relaxed, but in future, annual
new investments
corresponding to 20-25% of existing capacity will be needed.
III. Supply/demand balance forecasts for major LCD components
(1) Glass substrates
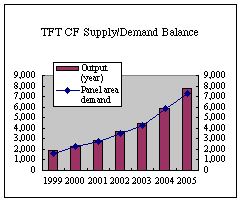
(2) Color filters
(3) Driver ICs
(4) Polarizing Sheets
(5) Backlights
The supply/demand situation for glass substrates and IC drivers
is currently soft, but in the long term the gap will close.
…¢.�@LCD Components Market Forecast
�@
Factors covered (for each component type):
(1) Market size forecasts (1998-2005), (2) Applications, technical
trends, (3) Pricing trends, (4) LCD maker procurement trends,
etc., (5) Market share/competitive analysis (including relative
market share (RMS)) (6) In-house production trends, etc.
1. Glass substrates: Tight supply situation amidst growing
market. A few dominant green sheet suppliers. Economies of scale
to drive down white substrate pricing.
2. Thin film substrates: Panel makers will make in house
for TFTs. Shift to chrome-free for BM. market will contract.
3. Plastic substrates: Sub- JPY1 billion ($87 million)
market that will rely on cellular phones for growth.
4. Alkali encapsulation films: Mature STN, TN market means
no great growth prospects.
5. Target materials (ITO): With only a few dominant players,
and indium supply shortages, price drops are unlikely.
6. Electrode protective coatings: As STNs are now
mainly small, the market will shrink. A few dominant players.
7. Color filters: Capacity increases in Taiwan. Bleak demand
for TSN CFs. Toppan is highly competitive here, but the market
will be soft.
8. Pigment dispersive-type resists for color filters: Stable
growth.
9. Color filter pigments: Ciba is highly competitive here,
and price falls are not foreseen.
10. Chromium targets: Environmental issues mean a probable
shift to resin BM. Tosoh is extremely strong.
11. Color filter overcoat materials: Used in slit &
spin process. Per-unit usage decreasing. Monopoly market.
12. Photoresists: Possible resurgence of negative types.
Highly competitive market.
13. Orientation Coatings: Nissan Chemical's RMS is 1.5.
Three suppliers dominate the market.
14. Spacers: Competitiveness of Sekisui Fine Chemical of
special note.
15. Rubbing cloths: The rubbing process is a critical one.
Will a rubbing-free manufacturing process emerge?
16. Sealants (substrate adhesives): Coexistence of UV setting
and thermosetting. Mitsui Chemicals strong.
17. Liquid crystal encapsulants: Nippon Loctite has an
RMS of 1.7.
18. Liquid crystal materials (mixtures): Movement in VA,
ISP. A few dominant players, but competition between them is intense.
19. Optical films (polarizing films, phase shift films): Nitto
Denko is dominant in phase shift film. Field of view compensation
films set to grow.
20. Fluorescent lamp backlight units: A cluttered market
comprised of Stanley and small-/medium-sized players. Thorough
cost controls need to be implemented.
21. EL lamp backlight units: Growth in Japan hit the wall
in 2001 with the proliferation of color screen cellular telephones.
22. Light guide panels: Procured directly by LCD panel makers
too, who make backlight panels in-house. Various trends, including
LGP-less and prism sheet-less displays.
23. Dispersion sheets: Dominated by three companies. Price
drops not envisaged.
24. Prism sheets: Monopolized by Sumitomo-3M joint venture
in Japan. But will prism sheet-less displays emerge?
25. Touch panels: Market to grow rapidly for PDAs and large
panels alike.
26. Anisotropic conductive films: Dominated by two suppliers.
Use has commenced in COG mounting of pSi¥TFTs. Great growth prospects.
27. TCPs (TAB film carriers): Intense competition between
two top players.
28. Driver ICs: Huge investments in plants by leading players.
Entry of Taiwanese players. Industry restructuring will stabilize
supply/demand equation.
Ordering
details:
Reports are supplied in .pdf format via email or CD-ROM.
LCD Components Supply/Demand 2001 (120 pages):
US$2000-
Global LCD/FPD Market Strategies 2001 (126 pages):
US$2000-
SPECIAL OFFER:
Two-volume set: LCD Components Supply/Demand 2001 plus
Global LCD/FPD Market Strategies 2001 at US$3500-.
Send orders and enquiries to:
ai.comm
Asia Info Tsushinsha Pte. Ltd.
95 South Bridge Road
#10-32 Pidemco Centre
Singapore 058717
Tel 65-226-0912
Fax 65-226-3269
Email: ai-comm@excite.co.jp
Please indicate the report/s you would like to purchase. We will
invoice you and ship the report/s on receipt of payment by telegraphic
transfer.
Sample Data
--Component Market Structure and Unit Prices
| Component |
|
Market Structure |
|
In-house production | Other factors | Unit price movement |
| Top player share | Top three share | Top player RMS | - | - | 98-05 CAGR | |
| Glass substrates (white) | 40.8% | 80.3% | 2.1 | - | Economies of scale | -8.1% |
| Film substrates | 37.3% | 76.6% | 1.7 | Yes |
|
|
| Plastic Substrates | 86.2% | 100.0% | 6.3 | - |
|
-1.7% |
| Target materials (ITO) | 44.3% | 90.3% | 1.8 | - | Rare metal | 0.0% |
| Electrode protective coatings | 43.8% | 93.8% | 1.2 | - |
|
|
| Color Filters | 44.9% | 82.4% | 2.0 | Yes |
|
-14.1% |
| Pigments | 61.1% | >90% | 2.0 | - |
|
-2.5% |
| Chromium targets | 62.5% | 90.6% | 3.3 | - | Environmental factors/ substitutes | -4.4% |
| CF overcoats | 76.9% | >90% | >2.0 | - |
|
-5.4% |
| Photoresists | 39.4% | 88.7% | 1.1 | - |
|
-8.6% |
| Alignment films | 44.9% | 89.8% | 1.5 | - |
|
-5.2% |
| Spacers | 66.7% | 75.0% | 8.0 | - |
|
-4.5% |