Advanced Market Report
Infinite Technologies, Inc., (iTec)
is pleased to announce the impending release of its latest report,
Global LCD/OELD Components Report 2002, a companion volume
to its LCD/FPD Market Strategies 2002 report, which will be released
simultaneously. The latest report predicts that the global market
for LCD components will exhibit average annual growth of 10% from
2001 through to 2006, reaching a value of 1,124 billion Yen ($8.45
billion) by then. The report also predicts that the components
market will account for 24% of the overall LCD module market by
2006, compared with 30% in 2001, indicating component suppliers
will come under increasing pressure to lower prices.
A special feature of iTec's latest report is the focus on components
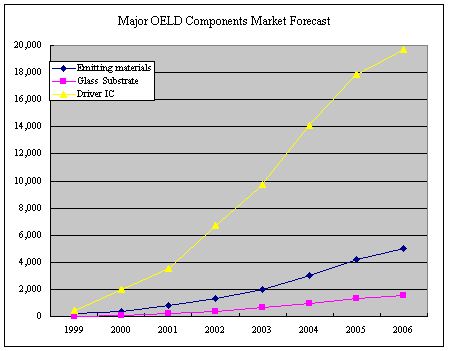
for organic EL displays. iTec forecasts that this market will
be valued at 225 billion Yen ($1.7 billion) by 2006. iTec principal
George Ohgaki says there is a high probability that driver ICs
will become a bottleneck in OELD production. The driver IC market
will be valued at an estimated 20 billion Yen ($150 million) in
2006.
iTec believes that plastic substrates, chrome targets, rubbing
cloths, sealants, and liquid crystal materials will be relatively
immune to drastic price falls. These markets are characterized
by the dominance of one or at most several players, the non-existence
of substitute materials, and no in-house production by LCD manufacturers.
On the other hand, prices for color filters, orientation coatings,
backlights, and light guide panels will tend to fall due to the
lack of dominant players, a competitive market, and in-house manufacture
at LCD manufacturers.
REPORT CONTENTS
AND SUMMARY
0. Executive Summary
1. Special Feature: Organic EL Display Components Market Forecast
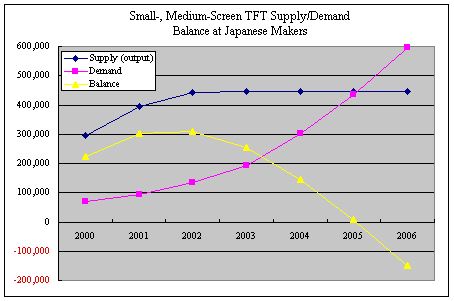
2. Supply/Demand Forecasts for TFTs
3. Major Bottlenecks in Expansion
of the LCD and an Overview of the Market Structure for Components
4. Supply/Demand Balance Forecasts for Major LCD Components
(1) Glass substrates
(2) Color filters
(3) Driver ICs
(4) Polarizing sheets
5. Forecasts for LCD Component Markets
Factors covered (for each component type):
1) Market size forecasts (1999-2006), (2) Applications, technical
trends, (3) Pricing trends, (4) LCD maker procurement trends,
(5) Market share/competitive analysis (including relative market
share (RMS)) (6) In-house production trends, etc.
1. Glass substrates: Strong players in both alkali-free and soda
lime glass. Large scale expansions in alkali-free glass are planned,
and unit prices are likely to fall 10%.
2. Thin film substrates: Panel makers will make these substrates
in house for TFTs. Shift from chrome to resin black matrix will
see market contract. Digging up new markets is a key challenge.
3. Plastic LCD substrates: Great growth potential, albeit from
a small base.
4. Alkali encapsulation films: Mature STN, TN market means no
great growth prospects.
5. ITO target materials: With only a few dominant players, and
indium supply shortages, price drops are unlikely.
6. Protective electrode coatings: As STNs are now mainly small,
the market will shrink. A few dominant players.
7. Color filters: While Toppan remains profitable in this market,
capacity increases in Taiwan should see a softening market.
8. Dispersed pigment color filter resists: Stable growth in line
with color filter demand growth.
9. Color filter pigments: Ciba is highly competitive here, and
price falls are not foreseen.
10. Chrome targets, resin black matrixes: While Tosoh is extremely
strong in chrome targets, environmental issues mean a probable
shift to resin black matrix.
11. Color filter overcoats: Monopoly market. However, increased
use of slit & spin process means usage will likely decline
dramatically.
12. LCD Photoresists: Increased use of negative types for fine
patterns. Highly competitive, oligopolistic market.
13. Orientation coatings: Three suppliers dominate the market,
but it is highly competitive, and prices will tend to fall.
14. Spacers: Various types are available. Sekisui Fine Chemical
leads by a wide margin. Significant market growth.
15. Rubbing cloths: A monopoly market, but manufacturers' progress
towards rubbing-free processes makes this market an uncertain
one.
16. Sealants (substrate bonding agents): Mitsui Chemicals is outright
market leader. Price drops in this market, therefore, are virtually
unthinkable.
17. Liquid crystal encapsulants: Henkel Japan is the market leader.
Shift towards use of UV curing types.
18. Liquid crystal materials (mixtures): A few strong players,
but competition between them is intense. Highly specialized products,
so price falls will likely be insignificant.
19. Optical films (polarizing/phase-shift films): Rapid growth
in viewing-angle widening films mainly for large TFTs. Increased
supply capacity for PVA, TAC.
20. Fluorescent lamp-type backlight units: Expect changes in the
market. Production has started in Taiwan. Cost controls need to
be implemented swiftly.
21. EL lamp-type backlight units: Accompanying the proliferation
of color screens cellular telephones and PDAs, market prospects
are dim.
22. Light guide panels: Also supplied directly to LCD panel makers.
,Various market trends include LGP-less and prism sheet-less displays.
Prices expected to fall dramatically.
23. Dispersion sheets: Dominated by three companies. Price drops
not envisaged, but emergence of prism sheet-less, reflective types
will influence the market.
24. Prism sheets: Monopolized by Sumitomo-3M joint venture in
Japan. The emergence of prism sheet-less types, however, will
place downward pressure on prices.
25. Touch panels: Market to grow rapidly for PDAs and large panels
alike.
26. Anisotropic conductive films: Dominated by two suppliers,
so minimal price drops predicted. Use has commenced in COG mounting
of pSi-TFTs. Excellent growth prospects.
27. TCPs (TAB film carriers): Intense competition between two
top players. COF mounting to increase due to trend towards narrow
frame cellular and monitor screens.
28. Driver ICs: Supply capacity is in place. Tendency will be
towards supply of 480-output drivers for use in high definition
(SXGA or better) displays.
The English language version of Global LCD/OELD Components
Report 2002 is available as of April through Infinite Technologies'
global marketing agent, Asia Info Tsushinsha, in either hard copy
or .pdf document format. The report is priced at US$2,500-
Japanese language version is also available for the same
price.
For more information, please contact:
ai.comm
Asia Info Tsushinsha Pte. Ltd.
95 South Bridge Road
#10-32 Pidemco Centre
Singapore 058717
Tel. 65-535-5300
Fax. 65-226-3269
Email: ai-comm@excite.co.jp
To place an order, please fill out your contact details below
and fax back to +65-226-3269 (Singapore). We will invoice
you and ship the report on receipt of your payment by cashier's
check or telegraphic transfer.
Name:
Company:
Title:
Mailing address:
Telephone:
Fax:
Email:
Infinite Technologies, Inc. (iTec) was established in April 1999
by George Ohgaki, previously a consultant at Yano Research Institute.
The company's staff of six specialize in analysis of three key
areas: information technology; electronics; and new materials.
Major projects to date include consultation on marketing and R&D
strategies at major Korean electronic component manufacturers,
a study on merger & acquisition targets for European companies
in the Japanese automotive component manufacturer sector, a survey
on computer peripherals technology, an analysis of management
at major U.S. semiconductor manufacturers, and a report on B-to-B
and B-to-C E-commerce in Japan.
Sample data (Source: Infinite Technologies, 2002)
|
- |
2002 | 2003 | 2004 | 2005 | 2006 |
| Component bottleneck % | - | - | - | - | - |
| Glass substrates | 8.4% | 8.2% | 7.7% | 8.0% | 8.4% |
| Color filters | 1.0% | - | 5.8% | 5.8% | 7.8% |
| Polarizing films | - | - | - | 2.9% | 9.6% |
| Driver ICs | - | - | - | 2.0% | 6.1% |
| Assumed bottleneck | 8.4% | 8.2% | 7.7% | 8.0% | 9.6% |
--OELD Market by Screen Size
| - | 2000 | 2001 | 2002 |
| 0-3" | 350 | 2,510 | 5,250 |
| 3-5" | 180 | 310 | 800 |
| 5-9" | 20 | 180 | 400 |
| Small, medium total | 550 | 3,000 | 6,450 |
| 10-12" | 0 | 0 | 0 |
| 13-15" | 0 | 0 | 0 |
| Large Total | 0 | 0 | 0 |
| Grand Total | 550 | 3,000 | 6,450 |
| Passive-OELD | 550 | 3,000 | 6,450 |
| TFT-OELD | 0 | 0 | 0 |